Europe's AI Rewiring: The Business Technology Revolution
Finch Capital's second annual State of European Business Technology report examines how AI transforms support functions—HR, Finance, Operations, Legal, and IT—from cost centres into strategic growth engines.
Executive Summary: AI Drives 50% of Business Tech Funding
Market Shift
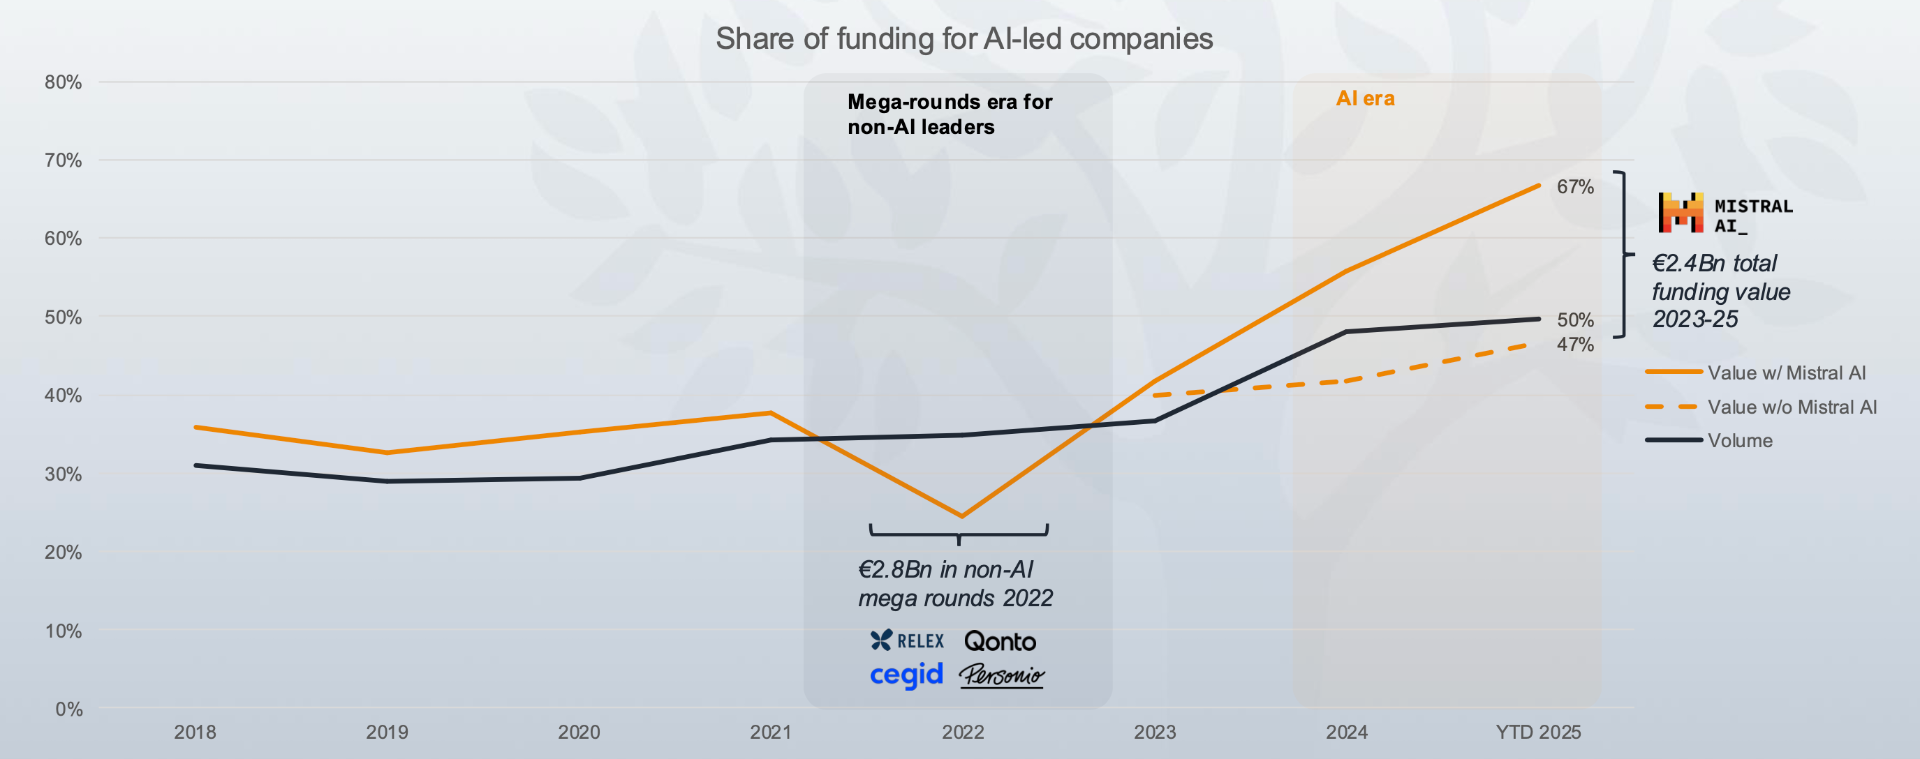
AI accounts for 50% of Business Tech funding volume in 2025. Median valuations surged 2.6× since 2018, surpassing 2021 peaks.
Deal Dynamics
Deal volume overall dropped 32% year-on-year. Yet deal values rose, showing consolidation amongst top performers across Europe.
Geographic Leaders
France leads deal value at 49%, driven by Mistral AI. The UK captures 33% of volume, followed by Germany and France.
Exit Landscape
Europe's median Business Tech exit reached €49M in 2025. Up 65% from last year, highlighting robust mid-market buyout activity.
AI's Structural Dominance: Reaching 50% of Funding Volume
2025 marks a tipping point in European Business Technology. AI-led startups now dominate funding in both volume and value. This structural shift signals a new era where AI agents and automation are now the main fuel for technology innovation across support functions.
Foundation Era
Traditional Business Tech maintained steady growth. AI represented less than 30% of total funding activity.
Acceleration Phase
AI funding climbed to over 30% of volume. Investment concentrated in infrastructure and foundational capabilities.
Dominance
AI reached 50% of Business Tech funding. Agents and automation become primary drivers of innovation and growth.
Sectoral Performance: Four Pillars of Business Technology
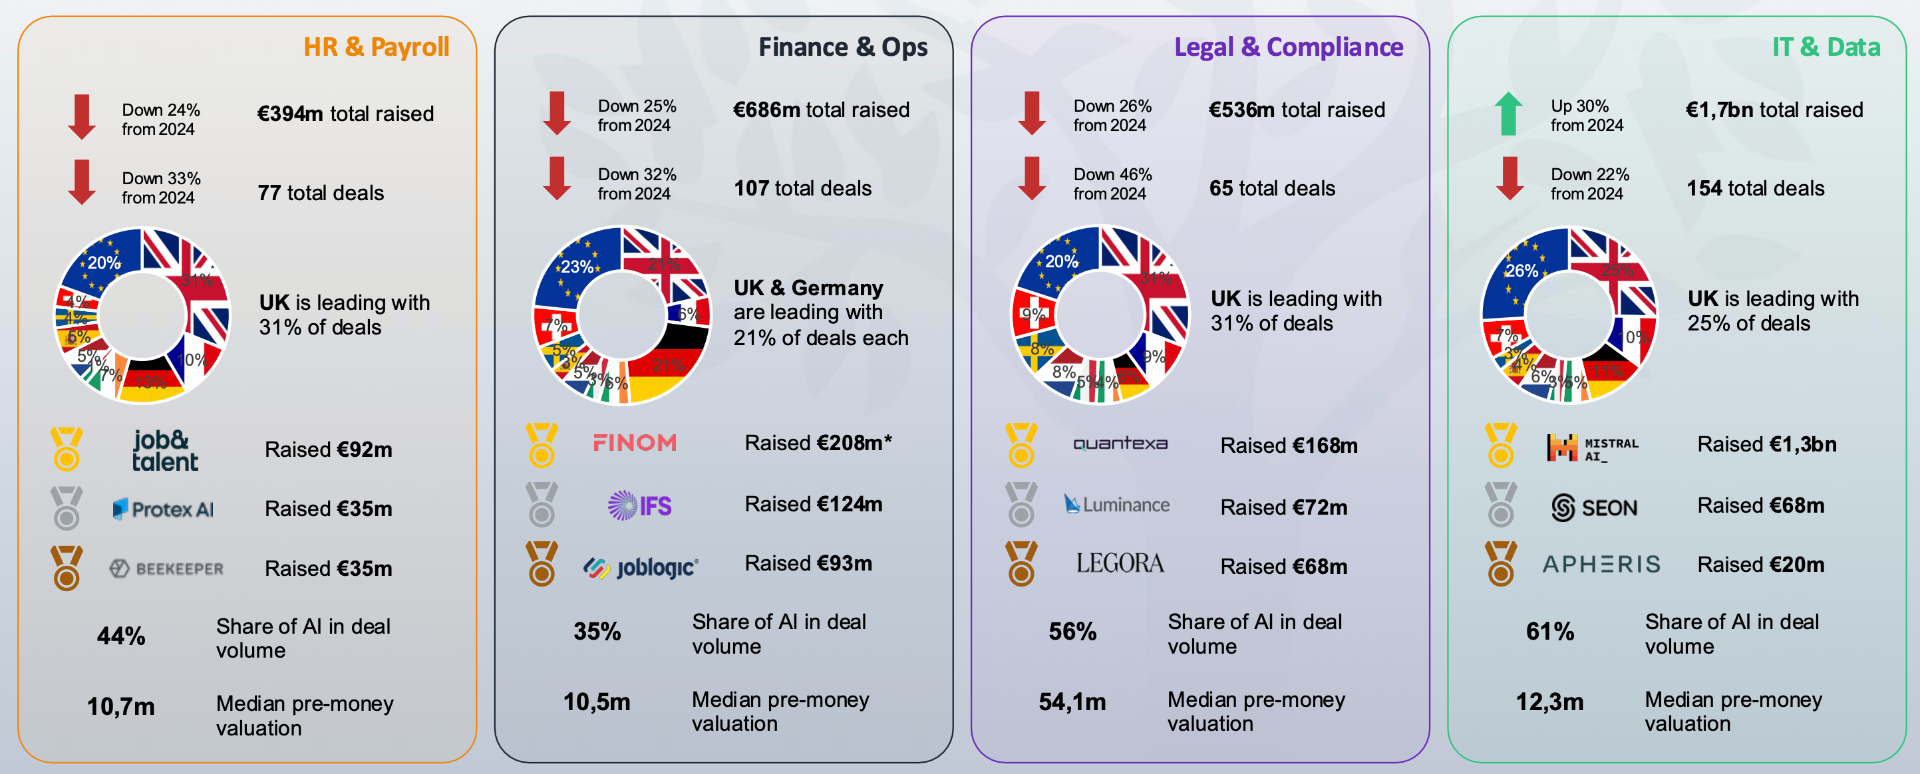
HR & Payroll
€394M raised in 2025 with €526M annualised, down 4% YoY, with the UK capturing 31% of all deals in the sector.
77 total deals to date, down 44% from the 2024 total, reflecting tighter capital deployment and concentration among top performers.
44% of HR & Payroll deals involve AI. Led by People Analytics and performance management platforms.
Finance & Operations
€686M raised in 2025 so far with €915M annualised, implying decrease of 15% YoY, with the UK and Germany jointly accounting for 42% of deals.
106 total deals to date, a 44% decline from 2024's total, with median pre-money valuations steady at ~€10.5M.
AI-related funding reached 35% of deal volume, led by digital procurement.
Legal & Compliance
€535M raised with €714M expected on an annualised basis, a decrease of 15% YoY, with 56% of deal activity AI-related
67 total deals to date, down 54% YoY, indicating a smaller but more strategic investor focus.
Surge in AI-driven IP management startups, attracting €15–€30M seed and Series A rounds across Europe.
IT & Data
€1.7B raised in 2025 to date, up 19% YoY with a quarter still to go, making it the fastest-growing Business Tech vertical.
157 total deals to date, down 37% on last year's total, as capital consolidates around AI infrastructure and data modernisation leaders.
61% of deal volume is AI-linked, snowballing enterprise demand for governance, cloud, and productivity AI tools.
Download the Full Report
Get comprehensive insights into Europe's Business Technology landscape with detailed analysis, charts, and sector-specific insights.
Valuation Dynamics: 2.6× Growth Since 2018
After a brief correction in 2023, valuations now surpass their 2022 peak. Driven by renewed AI optimism and proven models, median pre-money valuations surged across AI-led and traditional business tech companies alike.
Geographic Landscape: France, UK, and Germany Lead
This geographic distribution reveals distinct strategies. France bets big on foundational AI. The UK cultivates diverse applications. Germany focuses on industrial integration.
🇫🇷 France: Value Leader
Captures 49% of total deal value, driven by Mistral AI's mega-rounds. However, ranks only third in deal volume.
🇬🇧 UK: Volume Champion
Holds 33% of deal volume. Demonstrates breadth and depth of Business Tech ecosystem across all subsectors.
🇩🇪 Germany: Steady Performer
Holds 17% of deal volume. Strong focus on industrial applications and enterprise software infrastructure.
AI's Impact on Back-Office: 32% Value, 40% Automation
Whilst enterprises focus AI investments on core functions to drive top-line growth, back-office shows strong potential for value creation. However, only 5% of companies capture substantial value from AI due to lack of skills and true AI leadership.
Headcount declines, but skills shift upward. Winners build AI-ready cultures: agile, data-fluent, and rooted in human-machine trust.