Market Pulse November 2025
Strong all-rounded Q4 kickoff as October delivered balanced growth across Financial and Business Technology with sustained momentum in Lending, Payments, and Legal & Compliance.
Executive Summary
October delivered a strong all-rounded Q4 kickoff across European Financial and Business Technology, with 118 deals combined across both sectors showcasing balanced growth driven by strategic mega-deals and sustained investor appetite.
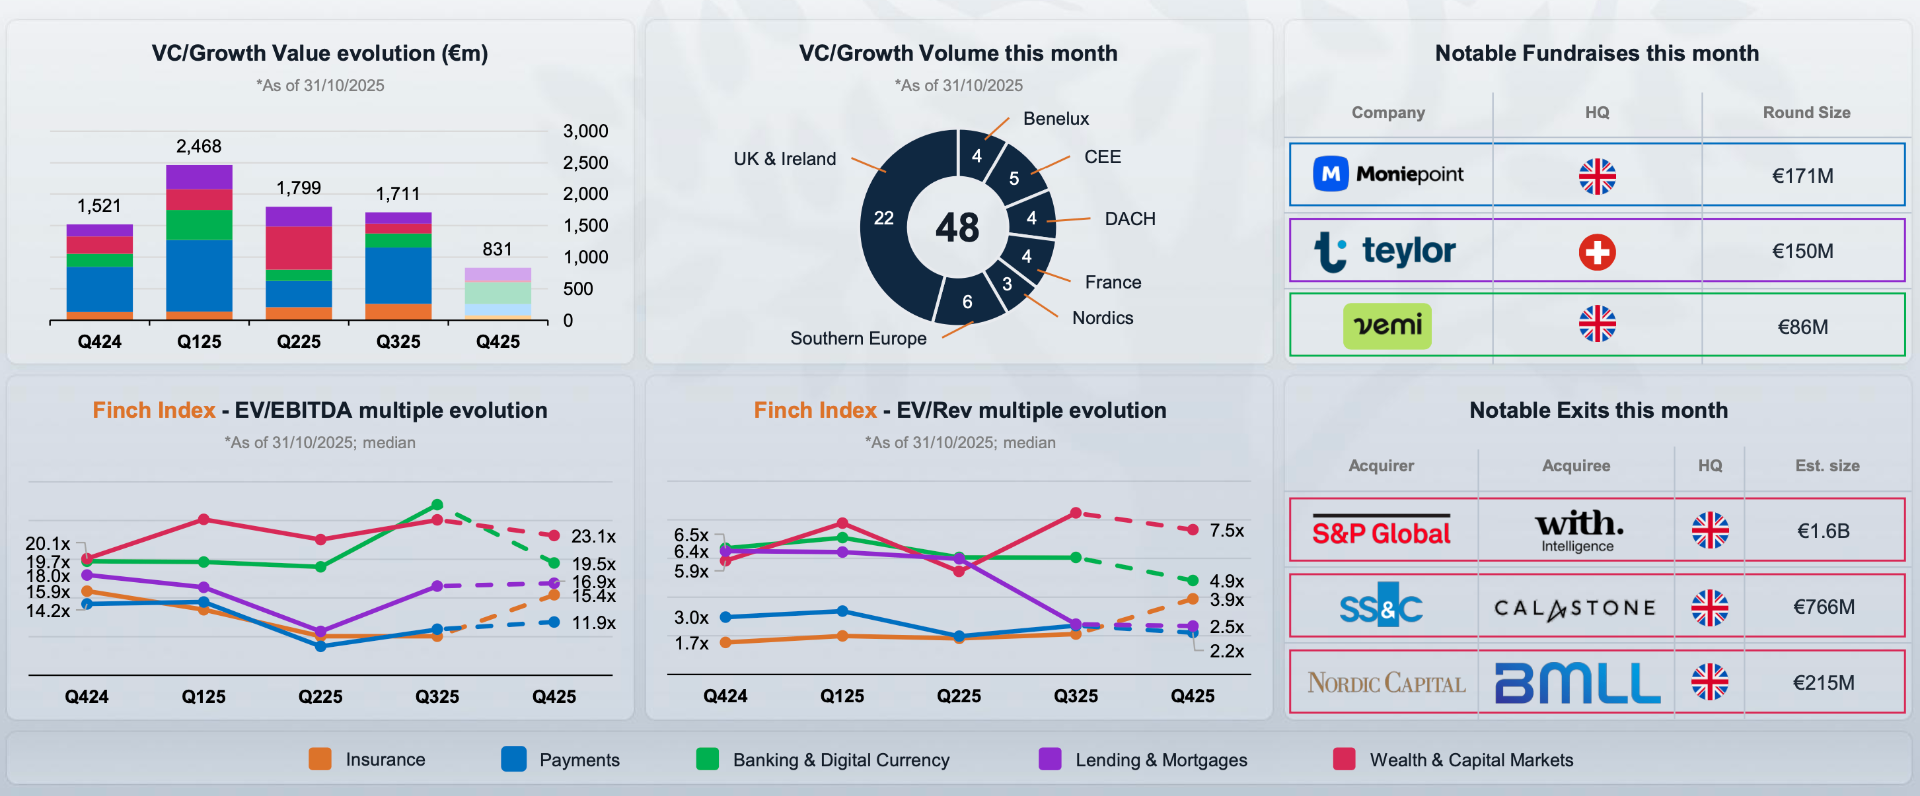
Fintech demonstrated remarkable resilience with 48 deals in total, led by teylor's €150M raise, Vemi's €86M round, and sizeable strategic M&A activity totaling. The sector maintained strong fundamentals with early Q4 activity showing promising momentum across Payments, Banking, and Lending.
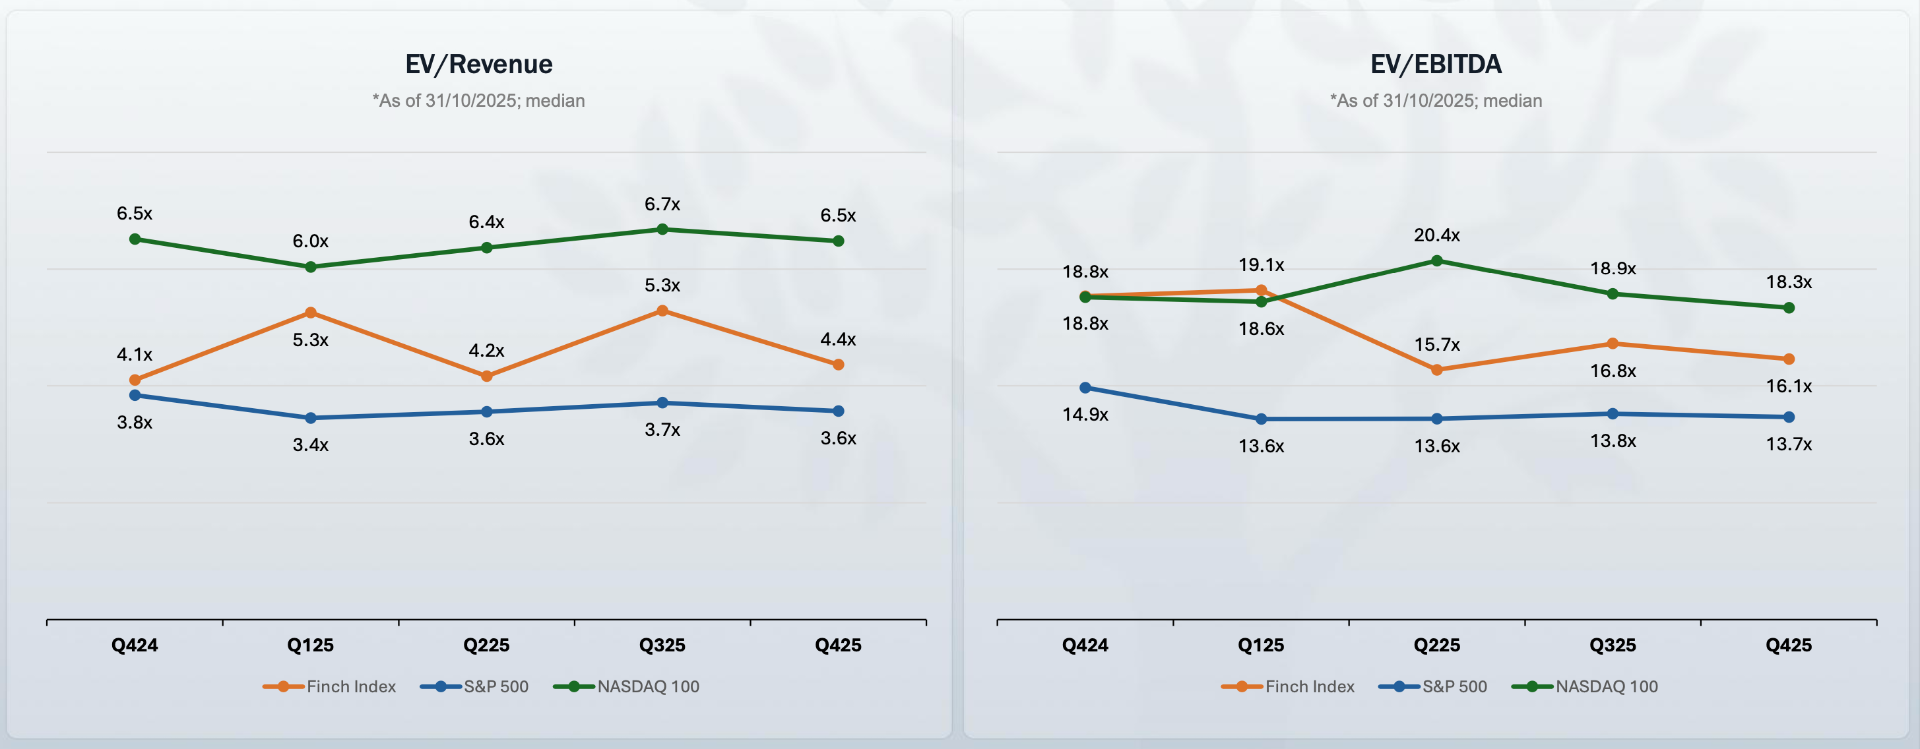
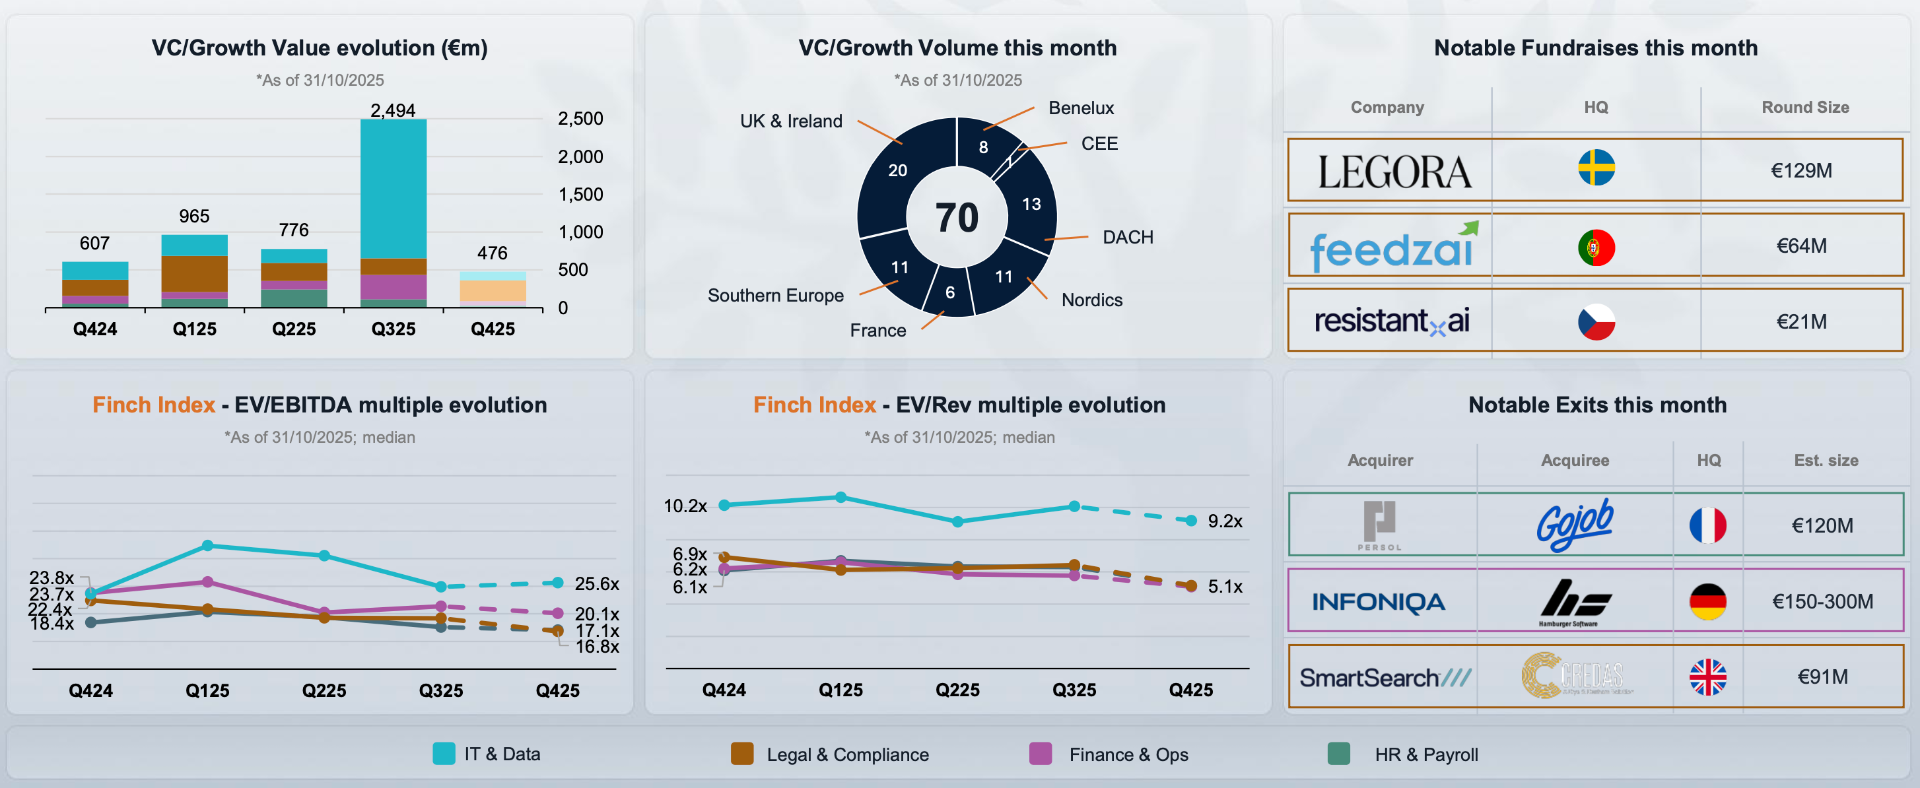
Business Tech saw robust performance with 70 deals, anchored by LEGORA's €129M Legal & Compliance mega-round and Gojob's €120M HR acquisition. The Finch Index held steady at 4.4x EV/Revenue and 16.1x EV/EBITDA, continuing to track closely with the NASDAQ 100 while maintaining its premium over the S&P 500.
Key Takeaways
- Strong Q4 Start with Balanced Growth: October saw 118 deals across both Fintech and Business Tech. Early Q4 momentum is signalling sustained investor confidence as the year draws to a close.
- Mega Deals Drive Market Activity:
- • teylor raised €150M for SME lending platform expansion
- • LEGORA secured €129M for Legal & Compliance technology
- • Gojob acquired for €120M in HR recruitment platform consolidation
- • Mryft's €171M raise boosted African payment infrastructure
- • S&P Global completed €1.6B acquisition of private markets data provider
- M&A Activity Intensifies: October saw significant consolidation across both Financial and Business Tech verticals. Key strategic acquisitions included TrueLayer's acquisition of Zimpler and Allica Bank's acquisition of Kriya in Payments (€50-150M range), and multiple exits across Wealth & Capital Markets led by S&P Global and Nordic Capital deals.
- Stable Valuations Across Sectors: The Finch Index maintained steady multiples at 4.4x EV/Revenue, with Insurance rallying and Wealth & Capital Markets showing strong performance. Business Tech demonstrated resilience with IT & Data maintaining premium valuations and Legal & Compliance attracting major investment.
Key Market Indicators
Finch Index Performance (Q4 2025) — Click to view full report
Financial Technology Summary
Financial Technology delivered a strong all-rounded Q4 kickoff in October, with 48 deals totaling €1.8B in disclosed value. Early Q4 activity already matches half of last quarter's funding, with particularly strong performances in Lending & Mortgages, Banking & Digital Currency, and Payments showing robust momentum across all major European markets.
Financial Technology Overview — Click to view full report
Financial Technology Sector Analysis
🛡️ Insurance Technology
Insurance Tech EV/Rev multiple rallied whilst funding reached expected heights. Notable deals included elr's €20M digital insurance risk underwriting platform, ISTANI's €17M SaaS platform for insurers, and an €11M raise for automated insurance claims management. The sector showed solid performance with balanced growth across risk management and underwriting platforms.
💳 Payments
Payments set a notable month for intercontinental expansion, led by Mryft's €171M raise for African business banking and payments infrastructure. Additional deals included €7M for unified payment processing for digital marketplaces and REasy's €2M seed round for international supplier payments. Strategic M&A included TrueLayer and Kriya acquisitions in the €50-150M range.
🏦 Banking & Digital Currency
UK dominates strong fundraising momentum with Vemi's €86M ethical digital banking platform leading the charge, followed by €51M for cloud-native core banking technology and Hyperlayer's €34M financial product builder software. The sector maintained robust growth with sustained institutional blockchain adoption and digital banking innovation.
📊 Wealth & Capital Markets
UK dominates flourishing M&A activity with S&P Global's €1.6B private markets data provider acquisition leading the segment, alongside SS&C's €766M CAiAStONE funds and settlement network deal and Nordic Capital's €215M BMLL capital markets data analytics acquisition. Venture activity remained steady with Depinsim, printr, and Beebop raising early-stage rounds.
🏠 Lending & Mortgages
Lending valuations nosedive amidst strong funding activity. teylor led with €150M for SME lending platform expansion, followed by TEYBRIDGE's €50M trade finance platform raise. The sector saw active M&A with ccreditclear's D acquisition and ARC EUROPE's M consumer finance platform deal, demonstrating continued investor appetite despite valuation pressures.
Business Technology Summary
Business Technology demonstrated strong momentum with 70 deals in total in October. Legal & Compliance dominated fundraising with LEGORA's €129M mega-round, while HR & Payroll saw significant M&A activity led by Gojob's €120M acquisition. The sector showed balanced growth across all major verticals with sustained investor appetite.
Business Technology Overview — Click to view full report
Business Technology Sector Analysis
👥 HR & Payroll
Gojob acquisition emerged as the highflyer this month with deel acquiring the €120M online job recruitment platform. Additional deals included €15M for a workforce upskill & e-learning platform, €8M for end-to-end workforce planning, and praxipal's €6M AI-powered healthcare management system. The sector showed consistent momentum with notable acquisition activity from pib Group.
💰 Finance & Ops
Finance & Ops demonstrated predictable performance supported by geographical deal mix. Key venture deals included €15M for inventory planning software, katana's €14M cloud-based inventory software raise, and €11M for a mobile-first AI suite to replace legacy platforms. Notable exits included INFONIQA's €150-300M ERP software acquisition and alerce's €13M Gadir logistics ERP deal.
⚖️ Legal & Compliance
Legal & Compliance dominated fundraising this month with back-to-back LEGORA deals. The sector led Business Tech activity with LEGORA's €129M mega-round in legal technology, supported by feedzai's €64M compliance platform raise. The segment saw significant activity from CEE and DACH regions, demonstrating strong cross-border investor appetite for legal tech infrastructure.
🤖 IT & Data
IT & Data maintained its position as a premium valuation sector with sustained activity in cybersecurity, data analytics, and AI infrastructure. The segment benefited from continued enterprise digital transformation spending and growing demand for data management solutions across European markets, maintaining strong fundamentals despite broader market uncertainty.
M&A Activity: The Real Story
M&A activity intensified in October with significant transactions across both Financial and Business Technology sectors, demonstrating sustained strategic buyer appetite and private equity interest in high-quality tech assets.
Key trends emerged: wealth and capital markets consolidation led by S&P Global and Nordic Capital; payments infrastructure acquisitions by TrueLayer and Kriya; and continued HR tech rollups exemplified by the Gojob deal.
Blockbuster Deals That Defined October
- 📊S&P Global Private Markets Acquisition: €1.6B — S&P Global's acquisition of a major private markets data provider marks the largest deal of the month, reinforcing the strategic value of alternative asset data infrastructure as institutional investors expand beyond public markets.
- 💰SS&C / CAiAStONE: €766M — SS&C acquired CAiAStONE's funds and settlement network platform for €766M, demonstrating continued PE appetite for financial infrastructure and operational technology consolidation.
- 📈Nordic Capital / BMLL: €215M — Nordic Capital's €215M acquisition of BMLL capital markets data analytics platform highlights growing demand for real-time market intelligence and trading infrastructure solutions.
- 💼deel / Gojob: €120M — deel's acquisition of Gojob online recruitment platform for €120M represents significant HR tech consolidation and validates the strategic importance of workforce management infrastructure across European markets.
- 🛡️Skyward / Apollo: €477M — Skyward's acquisition of Apollo, a specialist underwriting platform, reinforces ongoing M&A momentum in insurance technology, particularly around risk analytics and specialty lines.
- 💰Rapyd: €428M — Fintech-as-a-Service provider Rapyd raised €428M in a venture round led by XBO Ventures, reaffirming investor confidence in embedded finance and global payment infrastructure.
Investment Outlook
Momentum is building for a strong close to the year. The combination of resilient valuations, structural clarity in Business Tech, and renewed capital inflows points toward an acceleration in late-stage financings and exits. Expect continued focus on AI infrastructure, payments scaling, and vertical SaaS consolidation as strategic buyers stay active heading into 2026.
Download Full Report
Access the complete Market Pulse October 2025 report with detailed charts, methodology, and comprehensive sector analysis.
Download Report (PDF)